You've found a California home you can afford each month, but the down payment and closing costs still keep the purchase out of reach. Then you hear about California Dream For All eligibility and wonder whether the program can bridge that gap. The answer depends on more than being a first-time buyer. First-generation status, county income limits, residency, immigration status, credit, debt, and your plans for the property all matter.
Dream For All can be powerful for the right California hero, but it isn't free money and it isn't available to every hopeful buyer. The smart approach is to test your eligibility first, understand the future repayment cost, and get lender-ready before the application window opens.
What California Dream For All Actually Offers
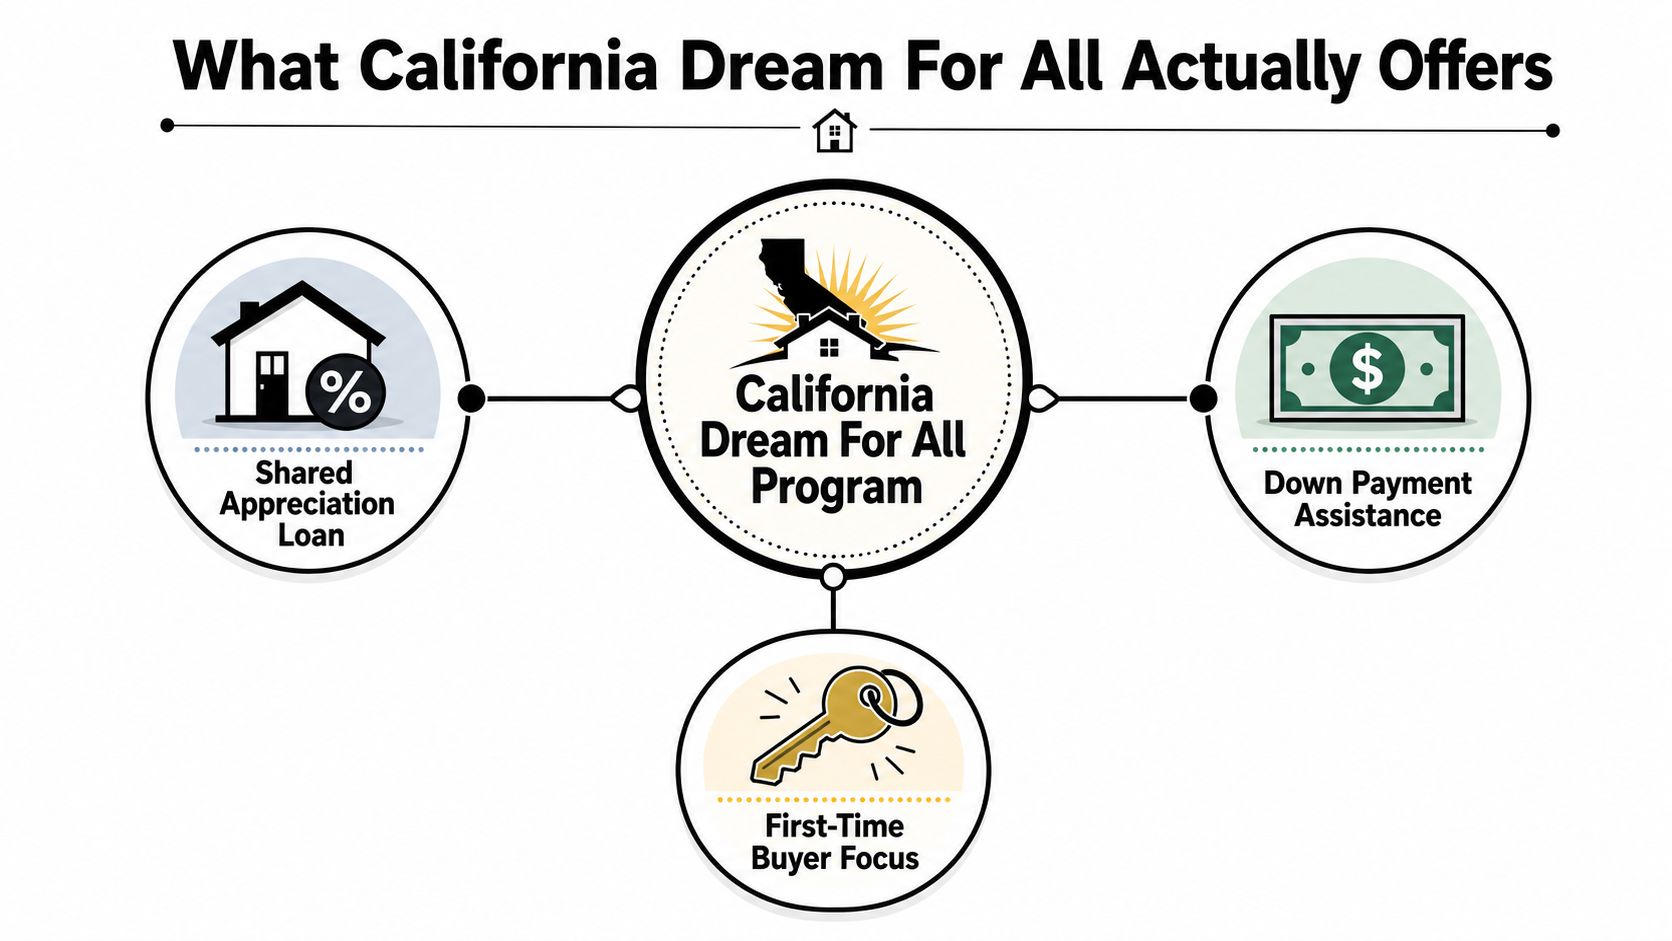
A California teacher, firefighter, nurse, or veteran may have stable income but still lack the cash needed to buy a home. Dream For All addresses that upfront barrier with assistance for the down payment or closing costs. The trade-off matters: this assistance is a shared appreciation loan, not a grant.
The program can provide the lesser of 20% of the home's purchase price or appraised value, and $150,000. It works alongside a first mortgage, reducing the cash required at closing and potentially improving your offer in markets where saving alone is difficult. CalHFA's program materials explain the assistance and repayment structure.
The loan has a future cost
Selling or transferring the home generally triggers repayment of the original assistance plus the same percentage of the home's appreciation. If the assistance equaled 20% of the eligible value used for the purchase, repayment generally includes the original amount and 20% of the appreciation under the program terms. Paying off the first mortgage can also make the obligation relevant, depending on the transaction and applicable rules.
That shared appreciation is the program's biggest financial trade-off. You receive help buying sooner, but you give up part of future price growth. A household expecting substantial appreciation should compare that future cost with the benefit of preserving cash today.
CalHFA's FAQ states that the combined transaction loan-to-value can range from 95.00% to 105.00%. The structure is designed for buyers who need substantial purchase financing, not households that can already draw on significant home equity. Review CalHFA's borrower eligibility guidance.
Who the program is really for
Dream For All serves a narrow group:
- All borrowers must be first-time homebuyers.
- At least one borrower must meet CalHFA's first-generation definition.
- At least one borrower must be a current California resident.
- Household income must fit the county-specific limit.
- Borrowers must meet citizenship or qualified immigration requirements.
County income limits can determine eligibility even when a borrower's income feels modest relative to local housing costs. Treat the program as targeted assistance, not a benefit every California buyer can claim. If you qualify, the upfront funds may change your purchasing power. If you do not, applying during a constrained registration period only wastes time.
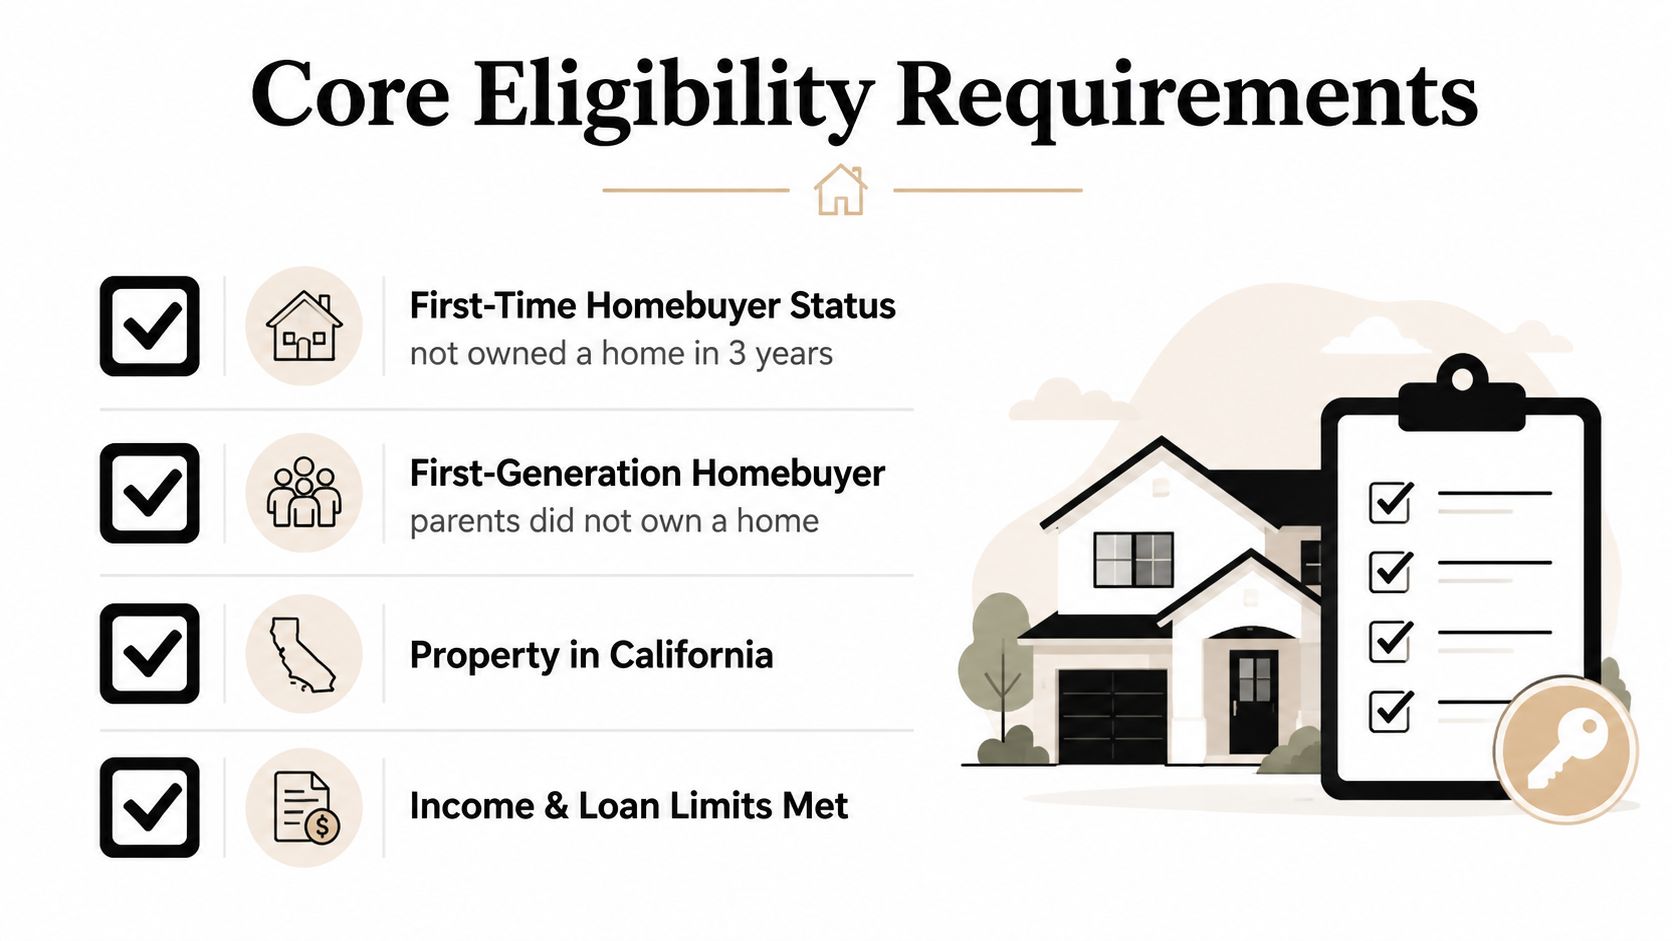
Core Eligibility Requirements Every Applicant Must Meet
A clean pre-screen prevents wasted time. California Dream For All eligibility depends on meeting every core rule, and one failure can stop the application before income or purchase planning matters.
First-time and first-generation status
Every borrower on the loan must qualify as a first-time homebuyer under the program's rules. The first-generation test reaches beyond whether you personally bought a house. An eligible borrower generally must not have held title, owned an interest, or appeared on a mortgage for a qualifying home in the United States during the previous 7 years. The property must have been a home on a permanent foundation with owned land. Review CalHFA's first-generation standard and related borrower rules before assuming you qualify.
A past co-ownership interest can count even if you never lived there. A previous mortgage can matter even after a sale. Give the lender your actual ownership and mortgage history, including inherited, jointly owned, or briefly held property.
California residency and borrower status
At least one borrower must currently reside in California. Every borrower must also be a U.S. citizen, U.S. national, or Qualified Alien under federal law, based on CalHFA's stated requirements. Confirm residency and immigration documents before registration. Finding a property first creates avoidable risk.
Credit and debt standards
Public reporting on the 2024 application round identified a 680 credit score requirement and a maximum 45% debt-to-income ratio. CalHFA's published income-limit materials provide the program context for these underwriting requirements.
Ask an approved lender to review your credit report, recurring debts, and full proposed housing payment. That calculation should include applicable taxes, insurance, and other required obligations. Credit-report errors can delay approval, while monthly debts can reduce the purchase price you can support.
The program's high-support structure helps buyers with limited upfront cash, but it does not replace underwriting. Review ownership history, income, credit, debts, residency, and immigration documentation before beginning a home search.
County Income Limits and How They Affect Your Household
Income eligibility changes with the county where you plan to buy. CalHFA's program uses a ceiling tied to 120% of area median income, rather than one universal statewide number. The 2024 relaunch tightened the ceiling, which means households that once assumed they were comfortably eligible may now sit near or above the limit. CalHFA describes the program's county-based eligibility framework.
The 2026 limits show how sharply the numbers differ by local housing market. CalHFA lists limits of about $148,000 in Del Norte County, $168,000 in Los Angeles County, and $309,000 in Santa Clara County. Read CalHHA's 2026 Dream For All income-limit announcement.
| County | Income Limit | Market Type |
|---|---|---|
| Del Norte County | About $148,000 | Rural and lower-cost |
| Los Angeles County | About $168,000 | Major metropolitan |
| Santa Clara County | About $309,000 | High-cost Bay Area |
The spread reflects local housing conditions. A household earning the same amount can qualify in one county and fail in another, even if the borrowers, professions, credit profiles, and purchase goals are otherwise identical.
How to read the cap
Use the income limit for the county where the property is located, not the county where you work or currently live. Household income also needs careful review because bonuses, overtime, commissions, self-employment income, and other earnings may be treated differently during underwriting.
If your income is close to the ceiling, don't assume a small change will be harmless. Ask the lender to calculate qualifying income under the actual program guidelines and to discuss how fluctuating earnings could affect the application.
The limit changes the strategy
A buyer near the cap in Santa Clara County may have more income room than a buyer with the same earnings in Los Angeles County, but that doesn't automatically make Dream For All the better choice. The larger allowable income may accompany a more expensive market and a larger future appreciation obligation. Use this California first-time homebuyer assistance resource to compare the broader assistance options, then have a lender test the numbers for your target county.
The Shared Appreciation Trade-Off You Need to Understand
Dream For All can solve the hardest part of buying, the cash required at closing. In exchange, the program takes a claim on future appreciation. Treat that claim as a major loan term, not a footnote.
Suppose a buyer receives the maximum $150,000 assistance and later sells the home for more than its purchase value. The buyer generally repays the original $150,000, plus the program's percentage share of appreciation. If appreciation totals $100,000 and the applicable shared percentage is 20%, the appreciation portion would be $20,000, before the program's exact calculations and transaction terms. Review the repayment formula carefully before signing.
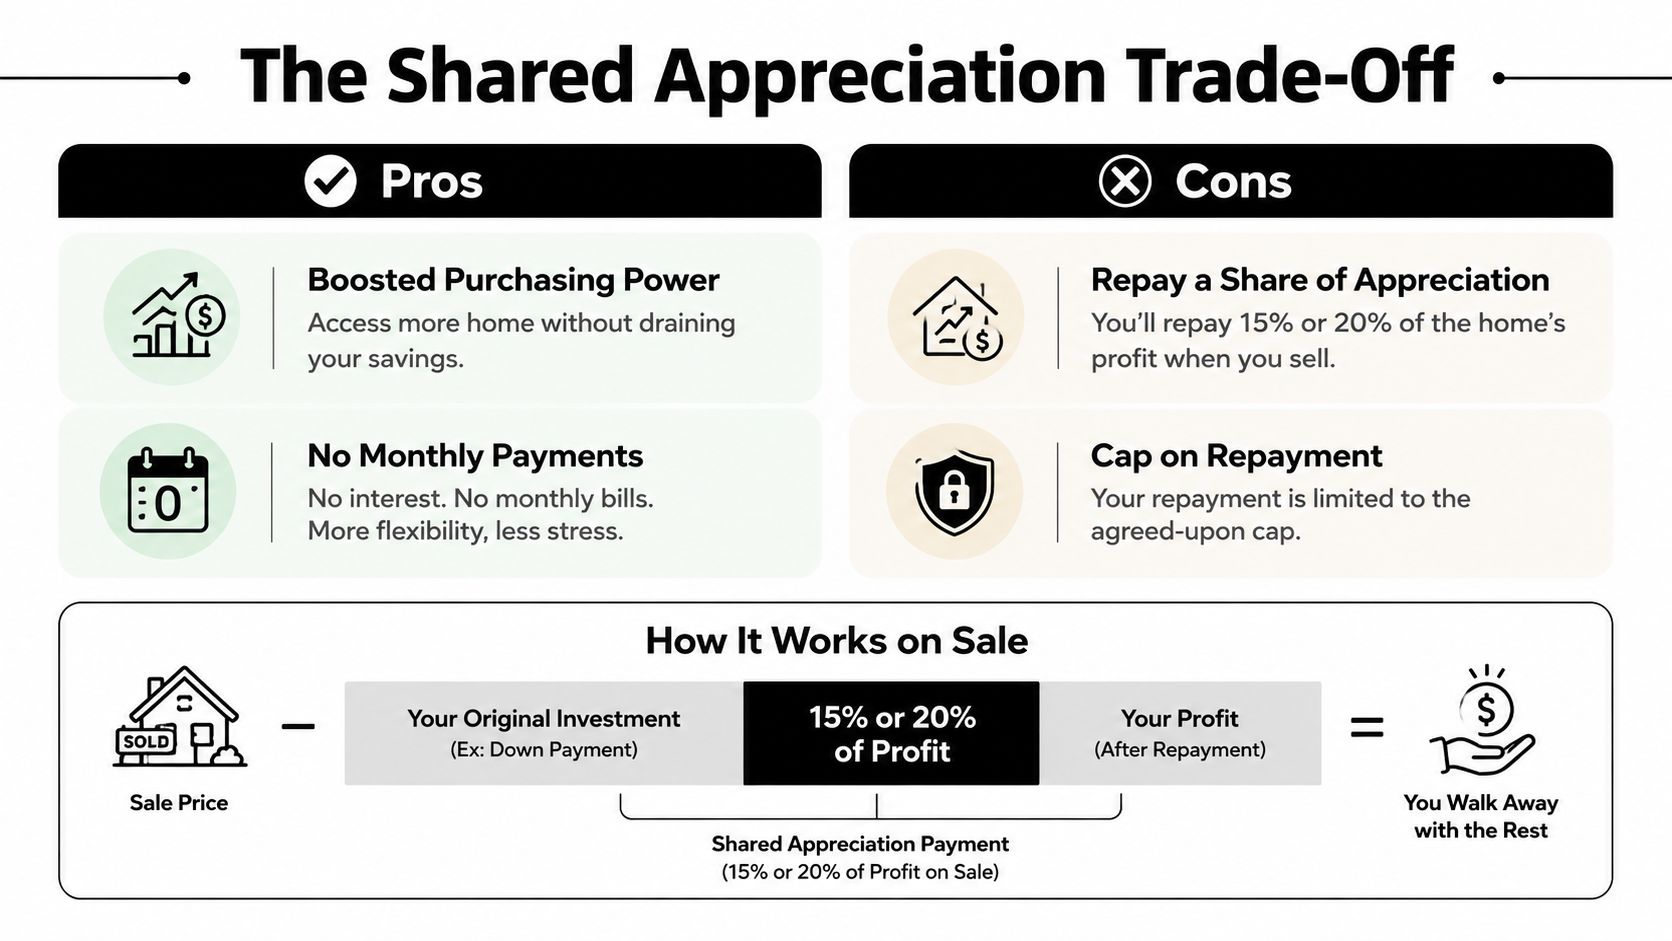
The cost can make sense if the assistance puts a sustainable home within reach and you expect to hold it for the long term. It becomes less attractive if you may sell or refinance soon, since either event can trigger repayment before you have built substantial cash reserves.
Ask what you're buying with the assistance
The useful question is not only, “How much down payment help can I receive?” Ask what that assistance changes in your household budget and long-term plan:
- Does the assistance make a sustainable payment possible?
- Will I likely stay in the property long enough to justify sharing appreciation?
- Could I repay the assistance if I refinance or transfer the home?
- Would another down payment strategy produce a better long-term result?
CalHFA reporting shows Dream For All represented over 70% of total assistance dollars while serving about 24% of borrowers in FY24-25, indicating that awards are relatively large and targeted. CalHFA's loan program reporting provides that assistance comparison.
For households near the county income cap in an expensive market, the upfront benefit can be compelling. A short planned stay changes the calculation. Compare the likely repayment with other assistance or down payment options before accepting the loan. CalHFA's shared-appreciation repayment guide can help frame that discussion, but your approved lender must calculate the obligation for your specific transaction.
Dream For All is best viewed as an equity trade, not a gift. You receive purchasing power today in exchange for sharing part of the home's future gain.
Documentation Checklist and Pre-Approval Steps
The registration process rewards preparation. For the 2026 cycle, CalHFA set the pre-registration window from February 24, 2026 through 5 p.m. PDT on March 16, 2026. Applicants had to work with a CalHFA-approved lender and obtain pre-approval before completing the portal application. CalHFA's 2026 bulletin lists the registration timing and lender requirement.
Start with the lender, not the portal. The lender can identify an ownership-history problem, calculate qualifying income, and determine whether your credit and debts fit the underwriting rules before you invest time in registration.
Build your file early
Prepare the documents your lender will need to verify:
- Income records: Gather recent pay information and documentation for overtime, commissions, bonuses, or self-employment income where applicable.
- Tax documentation: Provide the tax returns and supporting records the lender requests.
- Asset statements: Organize bank statements showing funds for required closing costs, reserves, or other transaction needs.
- Identity and status records: Prepare identification and documentation supporting citizenship, U.S. national status, or Qualified Alien status.
- Homeownership evidence: Collect records that clarify prior title, ownership interests, and mortgage history.
- Purchase information: Be ready to discuss the county, property type, occupancy plan, and estimated price range.
Follow a practical sequence
- Confirm the county. Your income limit depends on where you'll buy.
- Review first-time and first-generation status. Disclose every prior ownership interest and mortgage.
- Obtain lender pre-approval. Use a lender approved to originate CalHFA loans.
- Resolve documentation issues. Correct credit-report errors and explain unusual deposits or income changes.
- Complete the portal registration during the open window. Follow the instructions precisely and retain confirmation records.
A pre-approval isn't a voucher or a guarantee of assistance. It's the financial foundation that lets you move quickly if the program accepts your registration.
Real Scenarios Showing Who Qualifies and Who Does Not
Rules become easier to understand when applied to real household profiles. These examples use the stated income figures and eligibility standards, but a lender still has to verify each borrower's complete file.
The Los Angeles teacher
A teacher has a household income of $140,000 and plans to buy in Los Angeles County. That income is below the published 2026 county limit of about $168,000, so the household passes the county-income screen. If every borrower is a first-time buyer, at least one borrower satisfies the first-generation definition, and the household meets the residency, status, credit, debt, occupancy, and loan requirements, the teacher's household may qualify.
The income alone doesn't approve the application. It only clears one gate.
The Santa Clara firefighter
A firefighter plans to purchase in Santa Clara County, where the published 2026 limit is about $309,000. If the household earns more than that cap, the household fails the income test even if the borrowers are first-time buyers, have strong credit, and meet the first-generation rule.
A high county limit expands access for some households, but it doesn't eliminate the cap. The lender must use the program's qualifying-income calculation, not a rough estimate from a paystub.
The rural-county veteran
A veteran buys in a rural county and falls within the local income limit. However, the veteran co-owned a home five years ago. Because CalHFA's first-generation standard looks at ownership interests during the previous 7 years, that prior co-ownership can disqualify the borrower from the first-generation requirement.
Being a veteran, living in California, and meeting the income limit doesn't override the program's first-generation test. The borrower should ask an approved lender to review the ownership records and explore other assistance options rather than assuming Dream For All is available.
How California Loans for Heroes Simplifies Your Application
California heroes often have financial profiles that need careful interpretation. A firefighter may rely on overtime, a nurse may work variable shifts, and a teacher may receive income that requires documentation across multiple records. Those details can affect qualifying income, debt-to-income calculations, and the overall loan strategy.
California Loans for Heroes helps veterans, active-duty military members, first responders, law enforcement officers, firefighters, healthcare professionals, teachers, pilots, and public employees evaluate programs with that reality in mind. Through the HERO Home Loan & Buyer Rewards Program, the team offers one-on-one guidance, CalHFA-approved lending expertise, and comparisons between Dream For All and other down payment assistance options. Learn how California Loans for Heroes supports California public servants.
The practical advantage is clear. You get a documented eligibility review, a realistic payment analysis, and a plan for the shared appreciation obligation before you register or make an offer.
California Loans for Heroes can review your county income, first-time and first-generation status, documentation, and financing alternatives before you apply for California Dream For All. Visit California Loans for Heroes to start a one-on-one conversation and build a clear path toward homeownership.