Most advice about a special home loan in California starts with the wrong question: “Which hero program gives me the biggest benefit?” That approach treats VA loans, CalHFA assistance, CalVet financing, occupation-based offers, and local grants as interchangeable. They aren't.
The practical question is simpler. Do you need less cash at closing, a lower monthly payment, or both? A program that reduces upfront costs can increase the balance, rate, or later repayment obligation. A program that offers better pricing may leave you responsible for a larger down payment and closing costs. In California's high-cost market, choosing the wrong tradeoff can matter more than the program's marketing label.
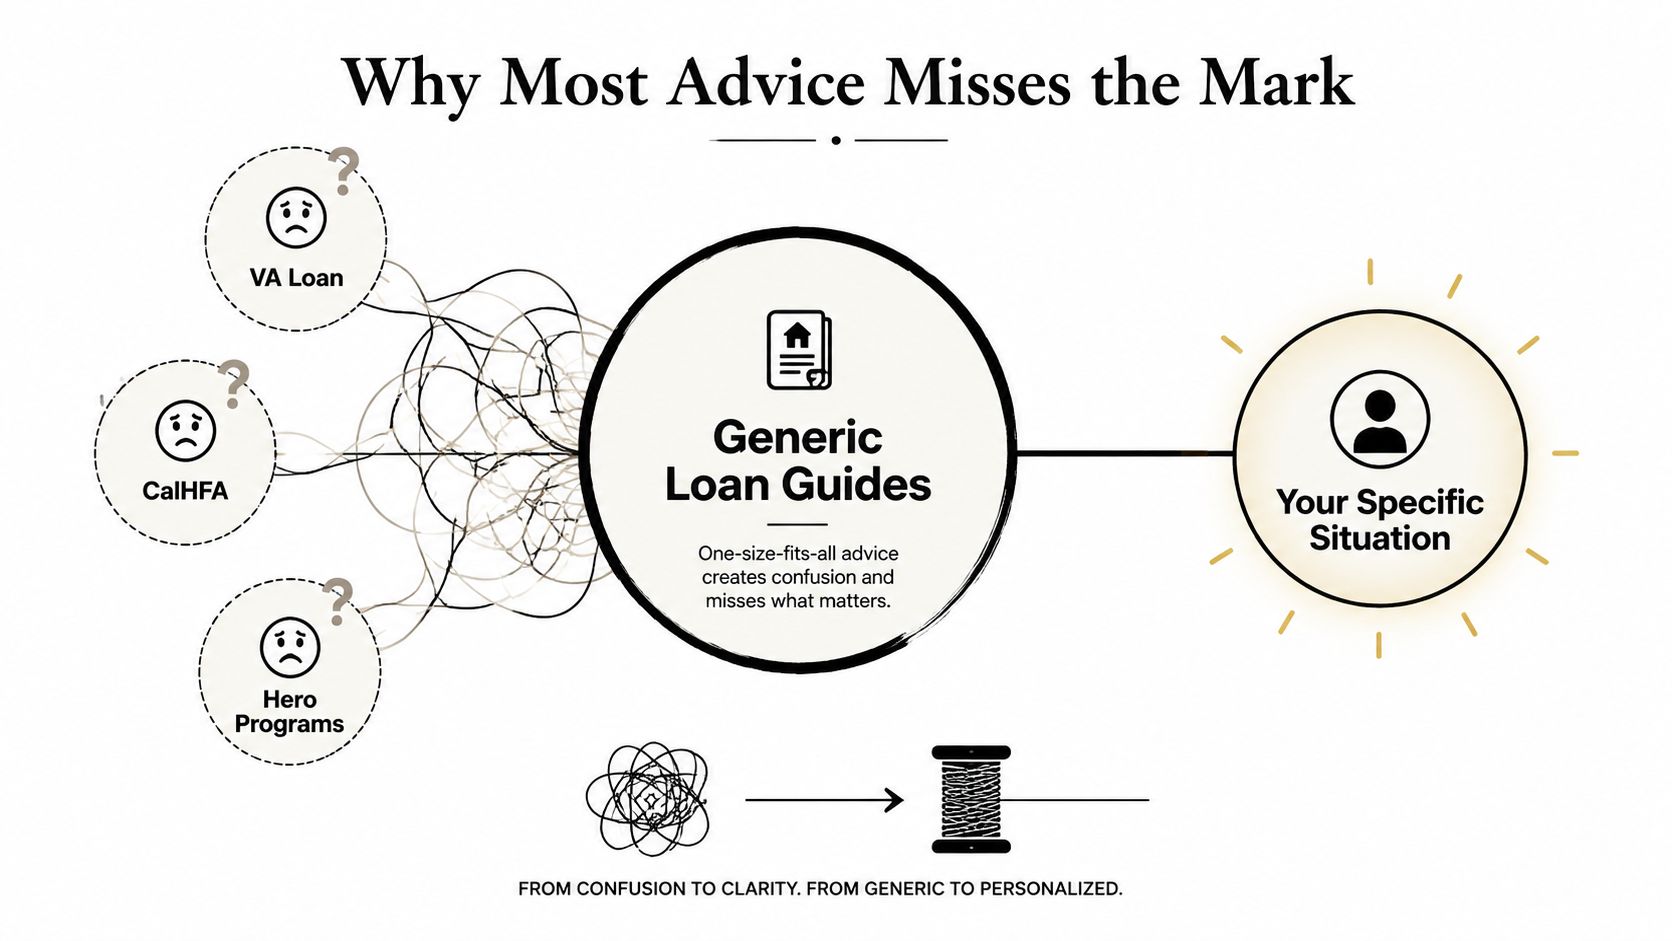
Why Most Special Home Loan Advice Misses the Mark
All hero loan programs aren't created equal. A veteran, teacher, firefighter, nurse, or public employee may qualify for a valuable benefit, but the benefit may solve a completely different problem from the one standing between that buyer and homeownership.
The first distinction is down payment assistance. CalHFA's MyHome program can provide a deferred-payment junior loan of up to the lesser of 3.5% of the purchase price or appraised value for eligible FHA transactions, with a separate 3.0% cap for conventional loans. The assistance can help with down payment or closing costs, but it isn't the same as a free discount. It sits behind the first mortgage and is repaid later, subject to program terms. See the CalHFA MyHome program details before treating the assistance as a grant.
Three paths solve three different problems
Profession-specific programs may offer rate reductions, lender credits, or fee savings to teachers, nurses, firefighters, law enforcement officers, veterans, and other public-service workers. A CalHERO-style offer can be relevant, but its value often depends on the first mortgage, lender pricing, employment documentation, and whether the program includes actual cash assistance. A lower fee doesn't automatically make a home affordable if the buyer still lacks funds for closing.
Federal programs include VA and USDA financing. VA is the standout option for eligible veterans and active-duty service members because the federal purchase benefit can allow no down payment when the sales price doesn't exceed the appraised value. The VA loan-limit guidance also explains how full and partial entitlement affect the amount a borrower can purchase without a down payment.
The third path is state and local assistance, including CalHFA, GSFA, city programs, and county initiatives. These can be powerful, but they may carry income, property, occupancy, lender, or repayment rules. The label “hero loan” tells you almost nothing until you identify the exact first mortgage, assistance structure, and total cost.
Practical rule: Judge a program by cash-to-close, monthly payment, repayment terms, and expected time in the home. Don't judge it by the word “special.”
California Special Loan Programs Explained
California buyers usually compare programs across four questions: who qualifies, how much cash the program contributes, what restrictions apply, and what the financing costs over the period they expect to keep the loan. The strongest option for one buyer can be a poor fit for another.
CalHFA MyHome is the clearest statewide down-payment-assistance example. It uses a deferred-payment junior loan, capped at the lesser of 3.5% for FHA loans or 3.0% for conventional loans, based on the purchase price or appraised value under the applicable program rules. It can reduce cash needed at closing, but borrowers must review county income limits, first-mortgage requirements, repayment conditions, and the effect of the second lien on future refinancing or sale.
CalHFA also offers a VA option with a CalHFA fixed-rate first mortgage, typically structured as a 30-year fixed-rate loan. That makes it worth comparing with a standard VA lender quote, especially when payment stability matters more than a narrowly advertised discount. The CalHFA Dream For All eligibility guidance is relevant for first-time buyers considering shared-appreciation assistance, but the program has its own income and application rules.
CalVet is different from CalHFA. It is a state veteran-focused loan program created by the California Legislature and signed into law on May 30, 1921. By its centennial, CalVet had helped more than 425,000 veterans finance California homes and funded more than $8.5 billion in mortgages, supported by 27 bond measures totaling just under $9.4 billion in approved funding, according to CalHFA's homebuyer program information. For qualifying veterans, CalVet can use the federal VA guarantee to offer up to 100% financing without monthly private mortgage insurance.
VA financing generally addresses the down payment problem directly. It doesn't mean every buyer gets every property approved, and partial entitlement can change the required contribution. The lender still evaluates income, credit, debts, assets, appraisal, and the property's condition.
Occupation-based programs such as CalHERO-style offerings may be useful when they provide lender credits, reduced fees, or rate advantages. They don't necessarily provide the deepest down-payment assistance. GSFA and local programs also need careful review because assistance may be structured as a grant, deferred loan, forgivable loan, or pricing adjustment.
| Program Name | Eligible Professions | Max Assistance | Income Limits | Real 5-Year Cost |
|---|---|---|---|---|
| CalHFA MyHome | Eligible first-time buyers, subject to program rules | Up to the lesser of 3.5% for FHA or 3.0% for conventional transactions | County-specific limits apply | Review junior-loan repayment, rate, mortgage insurance, and closing costs |
| CalHFA VA | Eligible borrowers using a VA-insured first mortgage | Depends on the applicable assistance structure | CalHFA limits apply | Compare fixed-rate pricing, fees, and any subordinate assistance |
| CalVet | Qualifying California veterans | Up to 100% financing may be available | Veteran service and discharge rules apply | Compare total pricing, fees, and long-term loan terms |
| CalHERO-style programs | Teachers, firefighters, law enforcement, nurses, veterans, active-duty service members, and other marketed professions | Program-specific, often fee or rate assistance | Program and lender rules vary | Calculate the value of credits or pricing against the first mortgage |
| Local hero grants | Eligible professions defined by the city, county, or sponsoring agency | Program-specific | Usually location and income dependent | Review funding limits, repayment, occupancy, and timing requirements |
Don't assume a larger advertised benefit creates greater savings. A deferred second mortgage can preserve your emergency reserves, while a rate discount can reduce the monthly payment for years. The right comparison uses the complete loan estimate, not just the headline assistance amount.
Cash to Close Versus Monthly Payment Tradeoffs
Every special home loan forces a choice between money needed today and money paid over time. Buyers often focus on the down payment because it's visible. The more expensive mistake is ignoring the first mortgage rate, mortgage insurance, subordinate-lien terms, lender fees, and the likelihood of refinancing or moving.
CalHFA assistance can reduce the amount a buyer brings to closing. That matters when savings are limited or when preserving reserves for repairs is more important than making a larger initial contribution. The assistance may also make a transaction possible when the buyer has stable income but not enough liquid cash for the full upfront expense.
A VA borrower with full entitlement may instead prioritize a zero-down structure. That can preserve cash without adding a conventional mortgage insurance payment, but the buyer still needs to budget for closing costs, prepaid items, reserves, and any required contribution caused by appraisal or entitlement constraints.
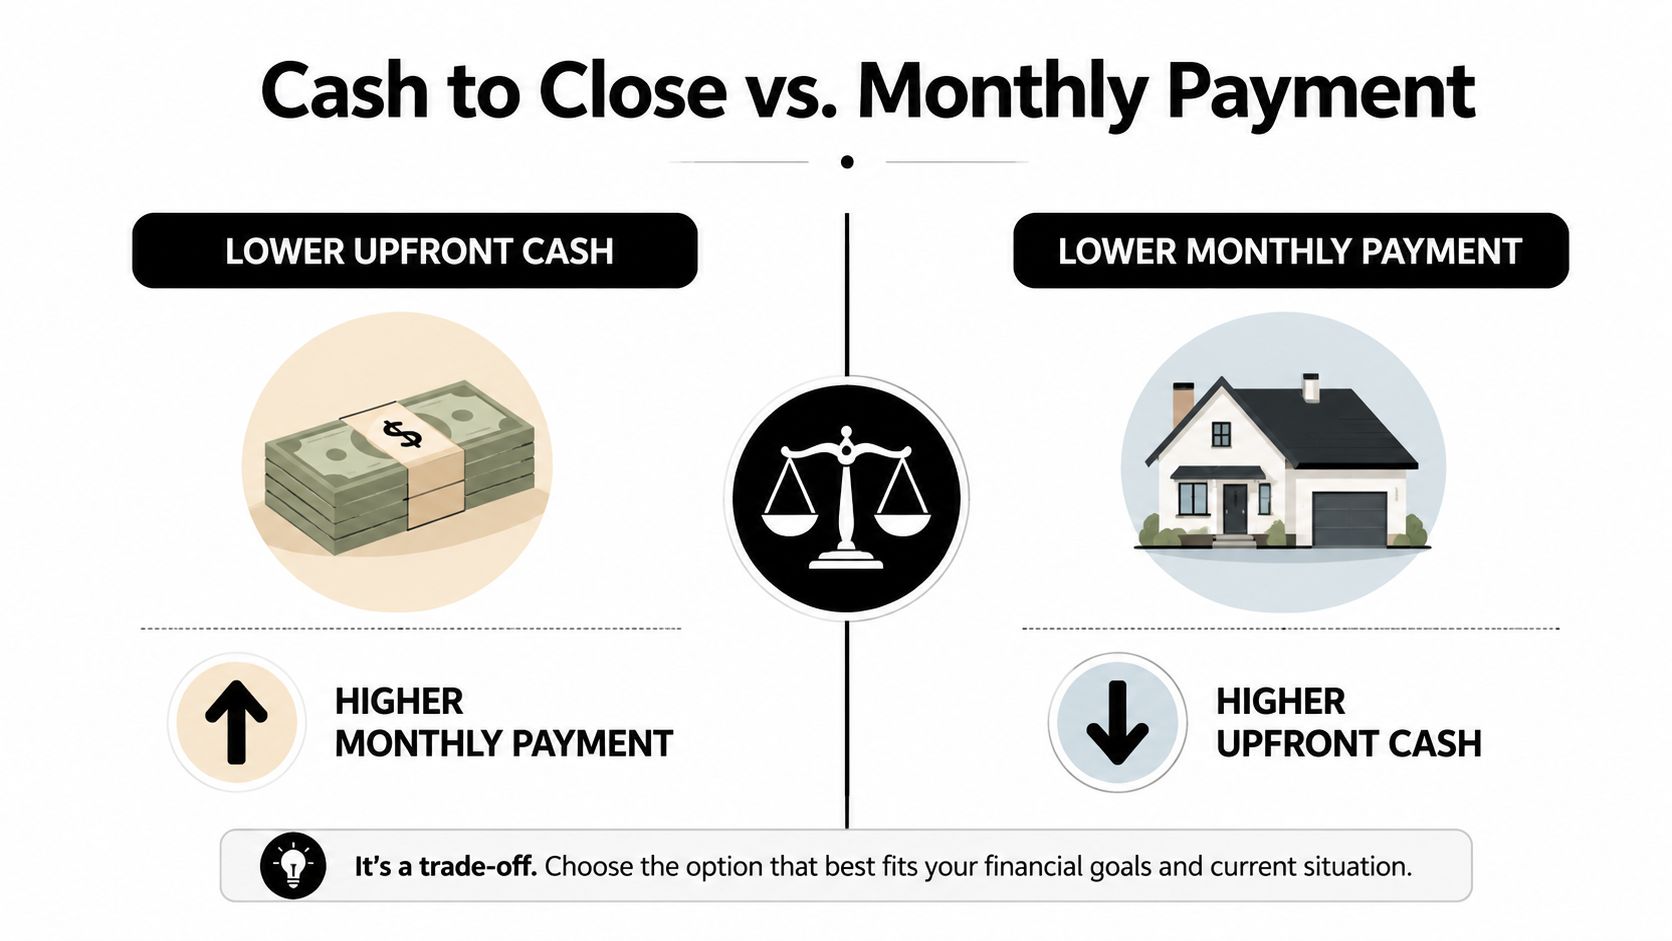
Calculate the break-even point
Don't accept a vague promise that assistance “saves money.” Ask the lender to compare two complete scenarios:
- Lower-cash option: Include the down-payment assistance, first-mortgage rate, mortgage insurance, subordinate-loan terms, lender fees, and estimated cash to close.
- Lower-payment option: Include the larger upfront contribution, reduced fees or rate, monthly payment, reserves remaining after closing, and projected loan balance.
- Break-even calculation: Divide the upfront cash preserved by the monthly cost difference. Then test whether you expect to stay in the property long enough for the tradeoff to make sense.
A buyer who expects to move soon may value cash preservation more than long-term payment efficiency. A buyer planning to remain for many years may prefer to bring more money to closing if the lower monthly obligation produces a stronger long-term result.
Ask for the five-year comparison, not the sales pitch. The comparison should show total payments, mortgage insurance, assistance repayment, lender credits, and remaining balances.
Lender credits can also change the calculation. A credit may reduce closing costs, but it can be tied to a higher rate or specific loan structure. Review what a lender credit is before treating it as free money. Stacking a profession-specific pricing offer with a local grant can work, but only when the programs permit combination and the resulting first mortgage remains competitive.
How to Qualify and Stack Your Benefits
Start with documentation, not house hunting. A lender can't identify the right special home loan California strategy without confirming service history, employment, income, debts, assets, occupancy, and the county where you plan to buy.
Build the eligibility file first
Veterans should gather service and discharge records, including the DD-214 where applicable, along with the documentation needed to establish VA eligibility. Teachers, nurses, firefighters, EMS professionals, law enforcement officers, and other public employees should prepare employment verification, recent income records, and any professional license or agency documentation requested by the lender.
Next, ask for a program-specific prequalification. Don't rely on a generic online mortgage estimate. The lender should compare VA, conventional, FHA, CalHFA, CalVet where applicable, and local assistance options using the same purchase price and property assumptions.
Stack in the right order
The first mortgage controls the structure. Determine whether the assistance can sit behind a VA, FHA, conventional, or other eligible loan before applying for a grant or subordinate loan. Some programs can combine, while others are mutually exclusive or require an approved lender, approved property, first-time-buyer status, or specific income documentation.
CalHFA income limits are not one statewide figure. CalHFA publishes county-by-county limits, and its 2026 income-limit table became effective on June 30, 2026, as shown in the CalHFA income-limit table. Check the limit for the actual county and program before you make an offer.
A practical file checklist includes:
- Eligibility records: Service verification, discharge documentation, employment letters, licenses, and program-specific forms.
- Financial records: Income documentation, bank statements, debt information, and explanations for unusual deposits or credit events.
- Program review: Written confirmation of income limits, property rules, repayment terms, funding availability, and whether benefits may be combined.
- Timing control: Rate-lock terms, lender approval, grant reservation requirements, appraisal deadlines, and closing-document coordination.
Don't apply for assistance in isolation. Have the first-mortgage lender confirm the entire stack before you commit to a property or assume a grant will fund on time.
For veterans comparing federal and state options, review the practical distinctions in VA home-loan down-payment assistance. A qualified specialist can also explain whether CalVet, CalHFA, a local program, or a standard VA loan creates the strongest overall result.
Real Scenarios for California Heroes
The following examples are planning illustrations, not verified borrower case studies. The exact payment, cash-to-close figure, rate, taxes, insurance, fees, and assistance amount must come from a lender's loan estimate. No honest advisor should promise savings before underwriting and property review.
A Sacramento public school teacher might compare a conventional first mortgage with CalHFA assistance. The buyer's priority could be preserving savings for moving expenses, repairs, and an emergency reserve rather than making a larger upfront contribution. The tradeoff would be a deferred junior loan, possible mortgage insurance, program fees, and a payment that may be less attractive than a standard conventional structure with more cash down.
A San Diego firefighter who is also an eligible veteran should compare CalVet and standard VA financing before looking at occupation-based offers. If full VA entitlement is available, the federal benefit may address the down-payment problem without monthly private mortgage insurance. CalVet could be worth reviewing as a separate state path, but the comparison must include rate, fees, property requirements, appraisal, closing costs, and the borrower's plan for renovations.
An ICU nurse in Los Angeles may need a different solution. A local assistance program paired with FHA financing could preserve cash for reserves, but the borrower must evaluate mortgage insurance, the assistance's repayment terms, property eligibility, income limits, and whether a conventional alternative offers a better payment. A profession-based rate or fee discount may help, yet it may not solve the upfront-cash problem by itself.
| Hero Profile | Home Price | Programs Used | Down Payment | Monthly Payment | Cash to Close |
|---|---|---|---|---|---|
| Sacramento public school teacher | Buyer-specific | Conventional loan and eligible CalHFA assistance | Determined by the first mortgage and assistance structure | Compare assistance structure, rate, and mortgage insurance | Reduced only if the buyer qualifies and assistance funds |
| San Diego firefighter and eligible veteran | Buyer-specific | VA or CalVet comparison, plus any permitted local benefit | Potentially no down payment with full VA entitlement and qualifying terms | Compare VA, CalVet, and occupation-based pricing | Closing costs and reserves still require planning |
| Los Angeles ICU nurse | Buyer-specific | FHA financing and permitted local assistance | Determined by FHA and assistance rules | Include mortgage insurance and all subordinate-loan costs | Depends on approved assistance, fees, and prepaid items |
The lesson is straightforward. The hero's profession opens doors, but the loan structure determines the financial result. Use realistic underwriting figures, not invented savings, when deciding.
Common Questions From California Homebuyers
Can I combine multiple programs?
Sometimes. A buyer may be able to combine a first mortgage with a subordinate assistance loan, lender credit, or local benefit, but each program has its own rules. Confirm compatibility with the approved lender before assuming the benefits stack. Some programs prohibit combination, require a specific first mortgage, or restrict refinancing and resale.
Do California income limits vary by county?
Yes. CalHFA eligibility uses county-specific income limits and updated program tables. A household can qualify in one county and fail the limit in another, even with the same income and household composition. Check the applicable table for the property county before relying on an assistance program.
Can I refinance after using assistance?
Possibly, but the junior loan or shared-appreciation obligation may need to be repaid, subordinated, or otherwise handled before the refinance can close. Ask for the program's written rules before selecting a loan based only on the initial cash benefit.
What happens if I change jobs?
A job change can affect underwriting, professional eligibility, income stability, or program compliance. Report the change immediately. A lender may need updated employment documents or may determine that an occupation-specific benefit no longer applies.
Are there options for high-cost California areas?
Eligible veterans with full VA entitlement generally don't face standard VA loan limits in California, so borrower qualification often becomes the primary constraint. Partial entitlement can produce a required down payment through the federal calculation. Other borrowers may need high-balance or jumbo financing, but hero status alone doesn't remove underwriting requirements.
Do special loans have hidden fees?
They shouldn't, but every cost must be reviewed. Ask for the official loan estimate and compare the interest rate, origination charges, lender credits, mortgage insurance, subordinate-loan terms, prepaid items, and any funding or program fees. Marketing language is not a substitute for a documented cost comparison.
When should I begin?
Begin before serious home shopping. Prequalification lets you identify viable programs, confirm county income eligibility, gather documents, and understand the cash requirement before you write an offer. A preapproval also needs to remain current, so ask the lender when updated income, asset, or credit documentation will be required.
Choosing the Right Path for Your Situation
Use three variables to make the decision: cash reserves, expected time in the home, and profession-specific eligibility.
If cash-to-close is the immediate barrier, start with CalHFA, local assistance, and any permitted subordinate-loan options. Confirm the repayment structure and compare the resulting payment against a standard first mortgage.
If long-term monthly cost matters most and you're an eligible veteran, start with VA and then compare CalVet where you meet its service and discharge requirements. If you're a teacher, nurse, firefighter, law enforcement officer, or other eligible professional, evaluate whether a hero-specific offer reduces the rate or fees enough to matter.
If flexibility is your priority, compare conventional financing with targeted grants or lender credits. A simpler loan can be easier to refinance or sell, but only if the upfront cash requirement fits your reserves.
Don't chase every advertised benefit. Select the one or two programs that fit your eligibility, property, timeline, and cash position, then compare complete loan estimates. California Loans for Heroes offers homebuyer assistance options, down-payment assistance, competitive mortgage rates, refinance solutions, lender credits, and one-on-one guidance for eligible California heroes. Visit California Loans for Heroes to discuss your options and get pre-approved with a team familiar with special home loan programs in California.