You've served in the Guard or Reserve, kept your civilian job, reported for drills, and completed annual training. Now you're looking at California home prices and wondering whether the VA loan benefit applies to you at all. That uncertainty is common, but waiting for a deployment or retirement can be a costly mistake. VA home loans for reservists follow specific service rules, and many California borrowers qualify through either completed reserve service or qualifying activation.
The process still demands careful documentation. Your drilling status, retirement points, discharge character, orders, funding-fee classification, and county-level affordability all matter. A lender who understands reserve records can identify the right eligibility route before you make an offer.
Understanding VA Loan Eligibility for Reservists
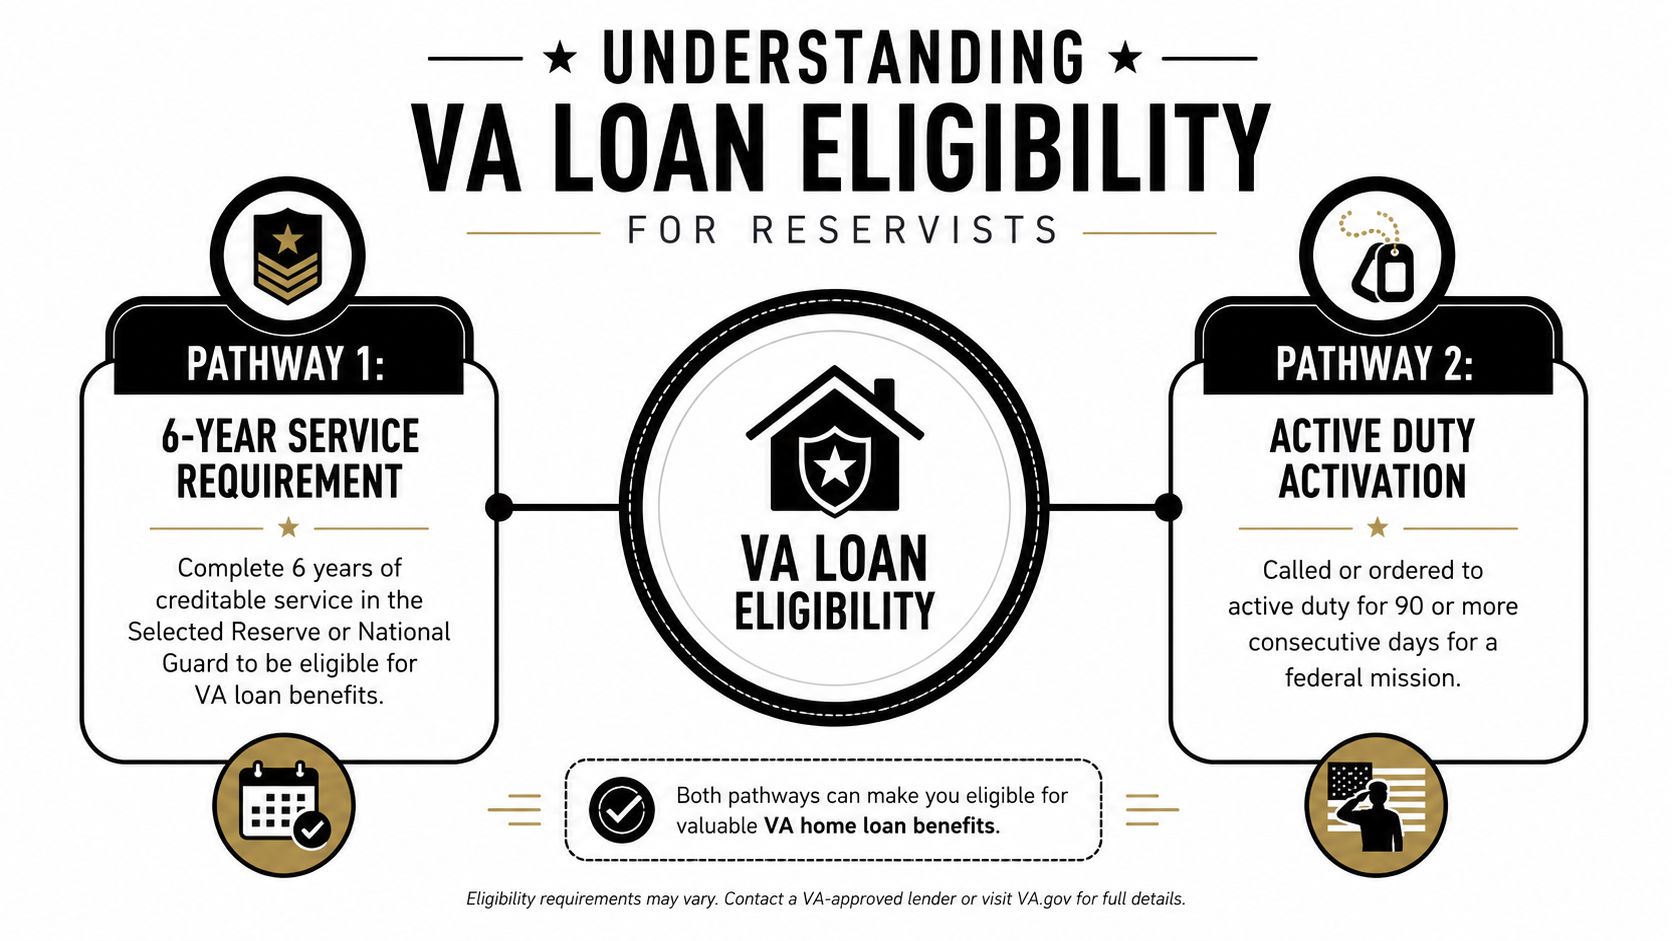
A reservist in California usually starts with one question: “Have I served long enough?” The better question is, which eligibility pathway matches my service record? If you aren't otherwise eligible through active-duty service, the VA generally recognizes a standard route based on 6 creditable years in the Selected Reserve, followed by an acceptable status such as continuing to serve, receiving an honorable discharge, being placed on the retired list, or transferring to another Reserve component after honorable service. The VA eligibility guidance also makes clear that inactive status doesn't count toward that requirement.
That distinction matters because reserve participation isn't just a label. Your unit membership, required drills, annual training, and documented service milestones help establish whether the years are creditable. A borrower can feel like they've “been in” long enough while the official record tells a different story, especially if there were breaks in service or inactive periods.
Start with the service record
The second major route is qualifying activation. Some reservists can qualify sooner through at least 90 days of non-training active duty or certain full-time National Guard duty performed under qualifying orders. The order type matters, so don't assume every period of active-looking service satisfies the VA standard.
Use this sequence:
- Review your component and status. Confirm whether you served in the Selected Reserve or National Guard and whether any period was inactive.
- Separate training from qualifying active duty. Initial training, drills, annual training, and activation can receive different treatment.
- Look for an earlier route. A qualifying activation may matter more than the calendar length of your reserve membership.
- Ask for a Certificate of Eligibility. The COE gives the lender an official starting point instead of relying on assumptions.
California's expensive housing markets make this review especially important. If you qualify, a VA loan may reduce the need to preserve a large down payment for a conventional purchase. You can also review how entitlement interacts with higher-priced properties through this guide to VA home loan limits.
Policy discussions are moving in the direction of broader Guard and Reserve access. The Congressional Research Service home-loan materials describe eligibility based on six years or qualifying full-time service, while the National Guard Association of the United States has reported on legislative efforts to expand access. Those proposals don't replace current rules, so make today's eligibility decision from your verified record, not from a bill that may change.
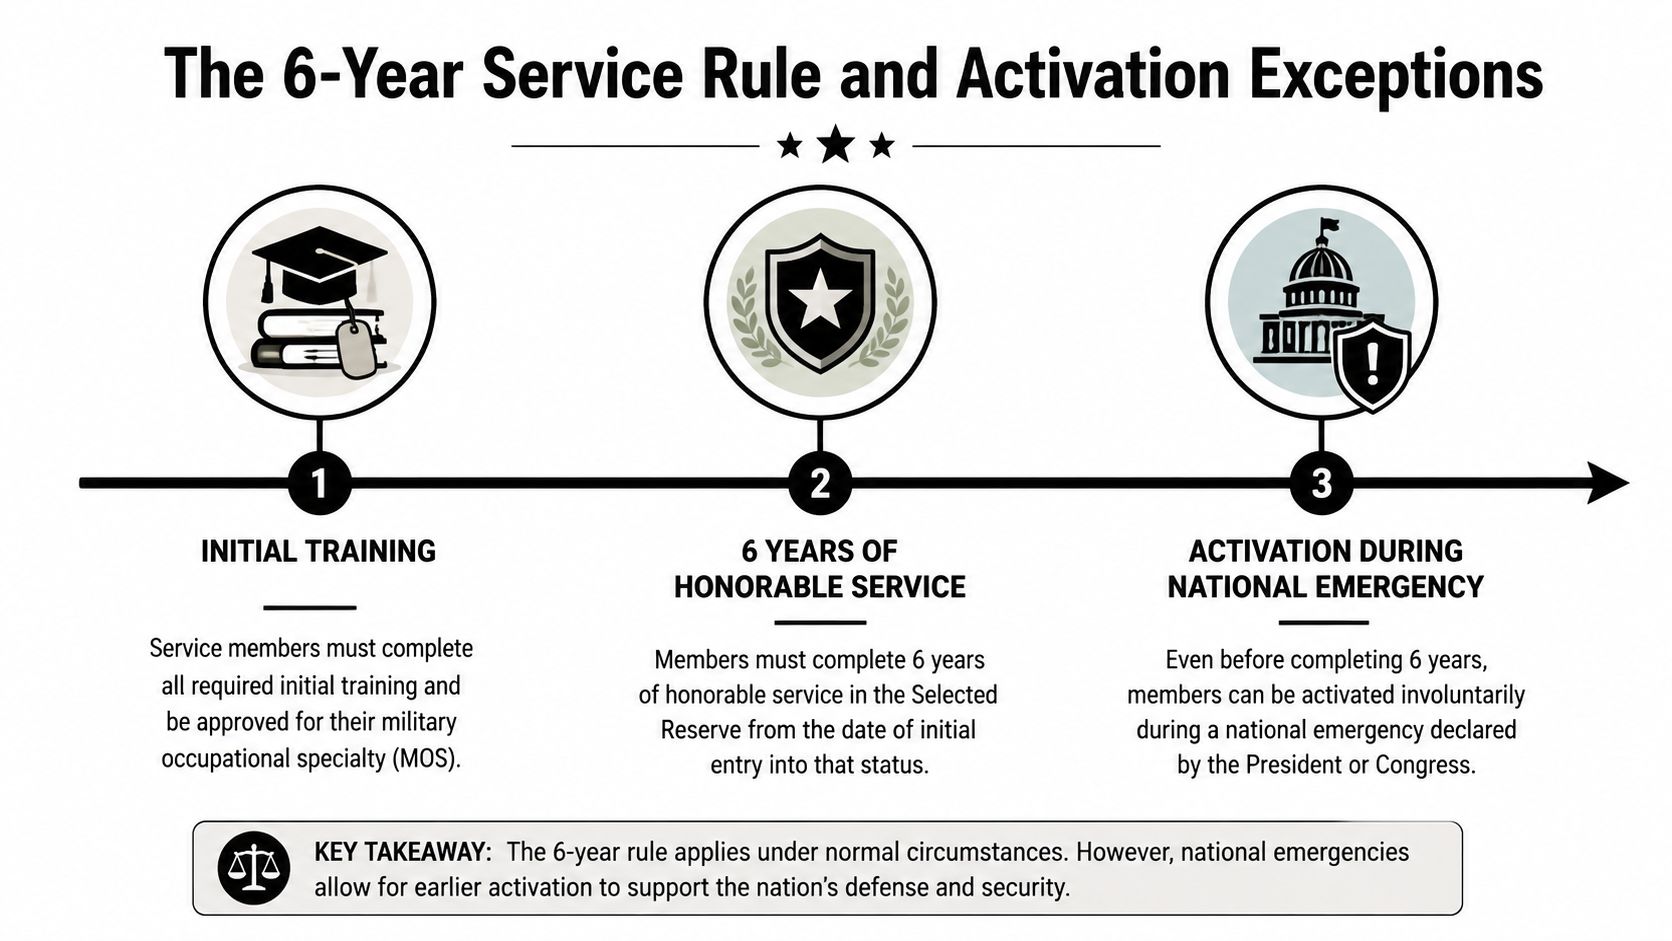
The 6-Year Service Rule and Activation Exceptions
A California reservist buying in a high-cost market cannot base eligibility on a general memory of service. The VA generally requires 6 creditable years in the Selected Reserve or National Guard when no other qualifying route applies. Your official reserve status, participation, and retirement-point records must support that service. The reserve eligibility guidance identifies an Army Reserve Chronological Statement of Retired Points and a Navy Reserve Annual Retirement Point Record as possible documentation.
Drills and annual training help show the reserve relationship recorded in your file, but they do not automatically produce the same eligibility result as qualifying active duty. Initial training, inactive periods, and activation orders require separate review. Missing records do not prove that you are ineligible. They do create a documentation problem that may delay a favorable COE decision.
Activation can change the analysis
Reservists who served after August 2, 1990 may qualify through a separate route. At least 90 days of active duty service can satisfy the minimum service requirement without relying on the six-year Selected Reserve rule, as described in the VA Buyers Guide. Army benefits guidance also states that Army Reserve members on active duty can become eligible after 90 continuous days following Initial Active Duty Training.
Two reservists with similar careers may therefore have different eligibility paths. One may need to complete six years and document honorable status. Another may qualify through an earlier activation. The controlling details are the legal character and continuity of the orders, not just the fact that the member served in uniform.
Practical rule: Match every service period to the official record, order type, and discharge documentation. Do not build a California purchase plan from memory.
Review this before turning preapproval into an offer strategy. In expensive California markets, confirmed VA eligibility can preserve cash that would otherwise go toward a conventional down payment. Ask the lender to determine whether your record supports the Selected Reserve route, the activation route, or further VA review before you set a purchase budget.
Getting Your Certificate of Eligibility
The Certificate of Eligibility, or COE, is the document that tells your lender whether the VA home-loan benefit is available based on your service record. It isn't the final loan approval, and it doesn't replace income, credit, asset, appraisal, or underwriting review. It does establish the eligibility foundation, which is why reservists should request it before shopping seriously.
Build the file before requesting the COE
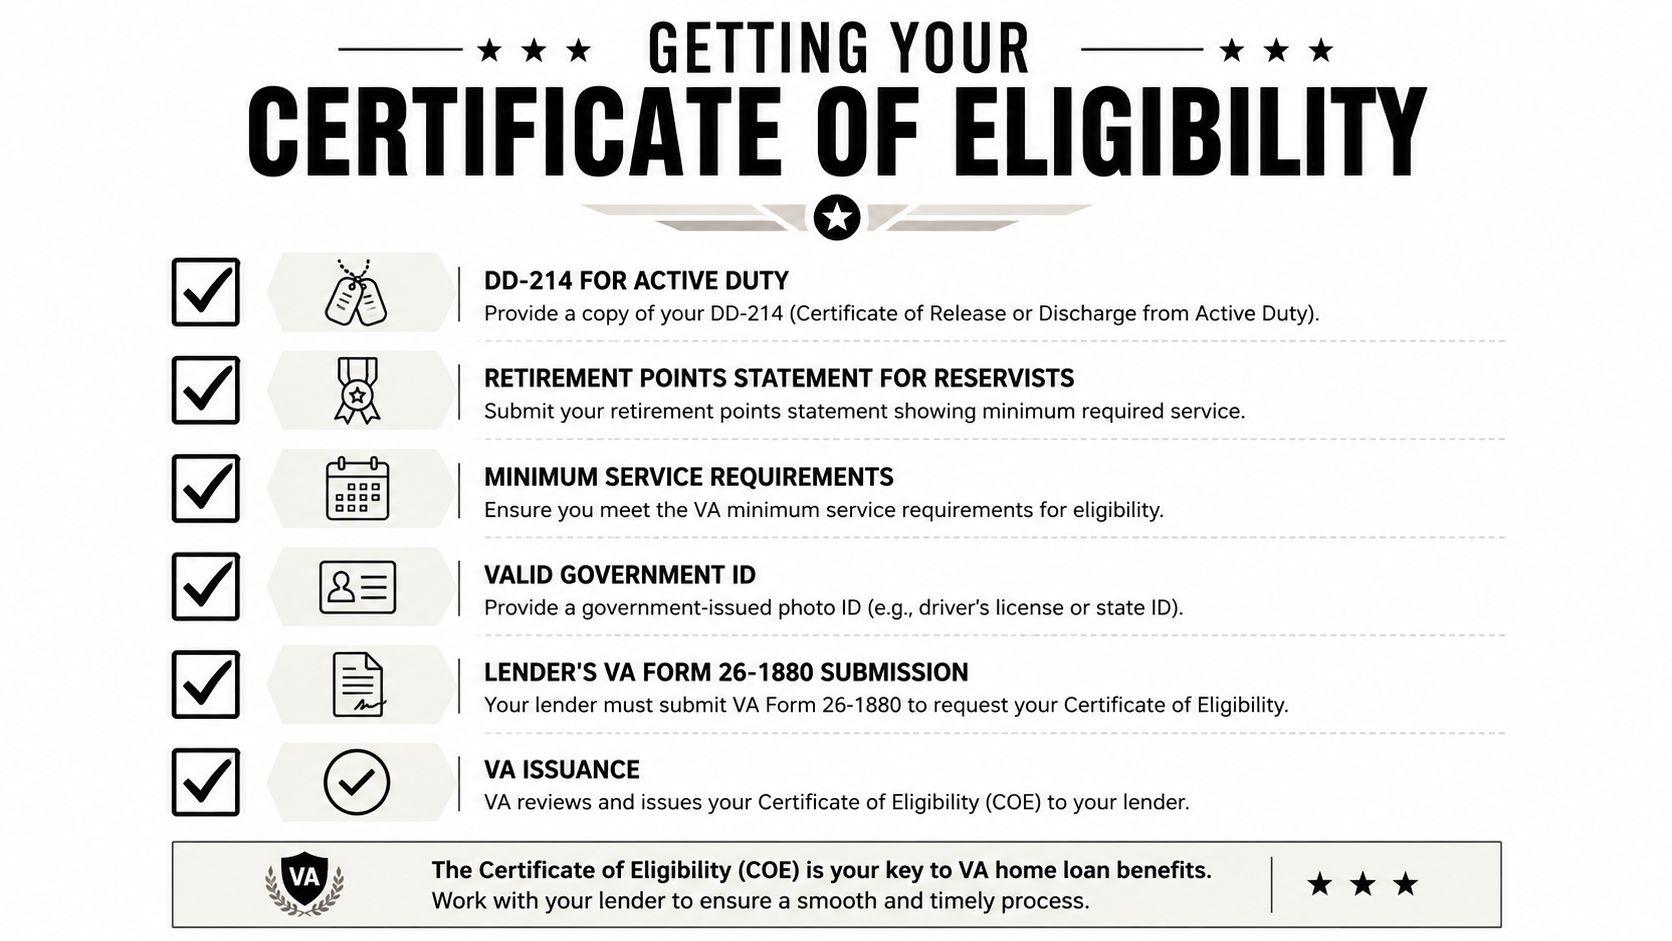
Start with the records that explain your reserve service. Depending on your branch and history, that may include a retirement-point statement, separation paperwork, active-duty orders, and documentation showing the character of your discharge or current service status.
A practical file-building sequence looks like this:
- Gather reserve records: Obtain the Army Reserve Chronological Statement of Retired Points, Navy Reserve Annual Retirement Point Record, or the equivalent record for your branch.
- Collect activation evidence: Include orders and separation documents for qualifying active-duty periods, especially if you believe activation creates an earlier eligibility route.
- Confirm your current status: Continuing service, honorable discharge, retirement-list placement, and qualifying transfer status can affect how the VA evaluates the six-year pathway.
- Submit through the right channel: You can request a COE through the VA, ask an approved lender to obtain it, or submit the applicable request by mail.
The lender route is often the most efficient starting point because the lender can review the COE alongside your mortgage file. If the automated process can't verify your reserve history, the lender can help package the supporting documents for manual review.
Fix an incomplete or unfavorable result
An “ineligible” result isn't always the end of the process. It may reflect missing retirement-point information, an unrecorded activation, an incorrect service-status entry, or incomplete discharge documentation. Ask the lender to identify the exact reason rather than accepting the result.
Contact your branch's personnel or records office for corrections, then provide the updated record for another VA review. If your history includes multiple components, transfers, or breaks in service, organize the timeline clearly. A short written chronology can help a reviewer connect records that were created by different offices.
Your COE should be treated as a records problem to solve, not a guess about whether your service counts.
VA Funding Fees and Down Payment Strategies
A California reservist buying in a high-cost market can face a large funding fee when the loan is structured with no down payment. If you are not exempt, compare the fee with the cash you need for closing, reserves, inspections, repairs, and moving costs before choosing a down payment. The VA funding-fee manual sets out separate Reserve and National Guard treatment on the Certificate of Eligibility.
For a Reserve or National Guard borrower who is not exempt, the stated tiers are:
| Borrower Type | Down Payment | Funding Fee % | Fee on $600K Loan |
|---|---|---|---|
| Reserve or National Guard borrower, not exempt | No down payment | 2.4% | $14,400 |
| Reserve or National Guard borrower, not exempt | 5% or more | 1.75% | $10,500 |
| Funding-fee-exempt borrower | Any eligible structure | 0% | $0 |
The table applies the stated percentages to a $600K loan amount. The fee tiers come from the VA manual, and the dollar figures are calculations based on that loan amount. A borrower with an exemption pays no funding fee, but the lender must verify the exemption instead of assuming it.
Putting 5% or more down generally reduces the fee from 2.4% to 1.75% for the applicable Reserve or National Guard borrower. That reduction can matter on a large California loan. However, using available cash for the down payment can leave too little for reserves or immediate home costs. Financing the fee may be permitted, but it raises the loan balance and can increase the payment and long-term interest.
Start by confirming exemption status. Then ask the lender to compare the total cash-to-close, loan balance, and monthly payment under each structure. Use this VA funding fee chart as a planning reference, then request figures based on your actual loan amount and transaction. California reservists should keep enough liquidity to handle the state's higher purchase prices and ownership costs, rather than choosing a down payment solely to reduce the fee.
Common Edge Cases and Misconceptions
Reservists encounter problems when generic VA explanations ignore service status and record quality. The most common misconception is that you must wait until retirement to use the benefit. You don't. Current service, honorable discharge, retirement-list placement, or a qualifying transfer can satisfy the status condition after the applicable service requirement, and qualifying activation may create a separate route earlier.
Inactive status is different. The VA says inactive status doesn't count toward the 6-year Selected Reserve requirement, so a borrower should review the official service timeline instead of counting every year associated with a reserve affiliation. If your unit records are incomplete, ask for the retirement-point statement and personnel correction before abandoning the application.
Situations that need a closer review
You're activated during the mortgage process. Tell the lender immediately. New orders can affect income documentation, employment verification, occupancy planning, and the timeline for underwriting. They may also provide additional evidence of qualifying service, but the lender must evaluate the exact orders.
You left service early. Early discharge doesn't automatically answer the eligibility question. The reason for separation, the amount and character of service, and any qualifying activation should be reviewed together. Request the COE and provide the complete separation record rather than relying on a verbal summary.
Your record shows fewer qualifying years than expected. Compare retirement points, unit membership, drills, annual training, and periods of inactive status. If the record is wrong, contact the appropriate branch records office and preserve every correction document.
You're tracking proposed legislation. Recent policy attention includes efforts to expand Guard and Reserve eligibility, including the National Guard Association's legislative coverage. Proposed changes may broaden access, but they don't replace the current VA rules. Apply under the standard pathways available today, then monitor official updates if your service record falls just short.
Maximizing VA Benefits in California's Housing Market
California reservists face a difficult combination: strong housing demand, high purchase prices, and competition from buyers who may offer cash or large down payments. A VA loan can still be a powerful tool because it may let you preserve cash while presenting a fully underwritten offer. The benefit works best when the lender, agent, and buyer address appraisal timing, property condition, occupancy, and financing terms before writing.
Expensive counties require a careful entitlement and payment review. Don't focus only on the absence of a down payment. Include the funding fee if you aren't exempt, property taxes, insurance, homeowners association costs, and the cash reserves you'll want after closing. Your maximum approval isn't the same as a comfortable California housing budget.
Make the offer competitive without overextending
A strong offer starts with a lender who can explain the VA financing clearly to the listing agent. Provide a credible preapproval, respond quickly to documentation requests, and keep contingencies aligned with the actual property and appraisal risk. Don't waive protections you don't understand just to compete with cash.
California assistance programs can also change the structure of the purchase. California Loans for Heroes offers the HERO Home Loan and Buyer Rewards Program, which provides access to homebuyer assistance, down payment assistance options, lender credits, competitive mortgage rates, refinance solutions, and dedicated support for military and public service professionals. Reservists can review VA down payment assistance options alongside other eligible programs, but every source of assistance must be checked for compatibility with the selected VA loan and property.
The right strategy may be no down payment, a targeted down payment that reduces the reserve funding fee, assistance that preserves your liquid assets, or a conventional comparison if the VA structure doesn't fit the transaction. Have the lender model those choices before you submit an offer, not after the seller accepts it.
California Loans for Heroes helps reservists and other California military and public-service professionals review VA financing, assistance options, lender credits, and purchase or refinance strategies. Visit California Loans for Heroes to connect with a team that can help verify your eligibility path and build a realistic homebuying plan.